
A Company Buys at the Till in Oman: Is It a Consumer Sale?
In Oman a company buying at a shop counter can be a consumer sale, with no Peppol invoice. What the architecture says, and when buyer details change that.
A company that buys something at a shop counter in Oman can be treated as a consumer sale. The Oman Solution Reference Architecture says so in terms: some consumer-sale buyers could be registered businesses, but "will still be treated as a B2C transaction", and its example is "a company purchasing stationary at a store". In that case the seller hands over a readable invoice with a QR code and reports the sale through its provider, and no invoice goes to the company over Peppol. But when the seller collects the buyer's details for a sale, a different invoice type applies.
This page is for a retail finance lead who has to decide what the till does when the customer is a company. It is built from section 4.1 and section 9 of the architecture, version 1.0.3 (final, 27 July 2026), the production PINT OM rule pack, and GoRoute's own platform code.
Is a company that buys at the till treated as a consumer?
It can be. Section 4.1 lists four notes on consumer sales. Note 2 is this one: "Some of these transactions could be B2B registered Peppol buyers, but will still be treated as a B2C transaction. For example, a company purchasing stationary at a store."
Put plainly, the buyer being a registered business does not by itself move the sale out of the consumer flow. What the sale is documented as depends on how it is handled at the counter. The consumer flow itself is explained in selling to consumers in Oman.
What can happen at the counter?
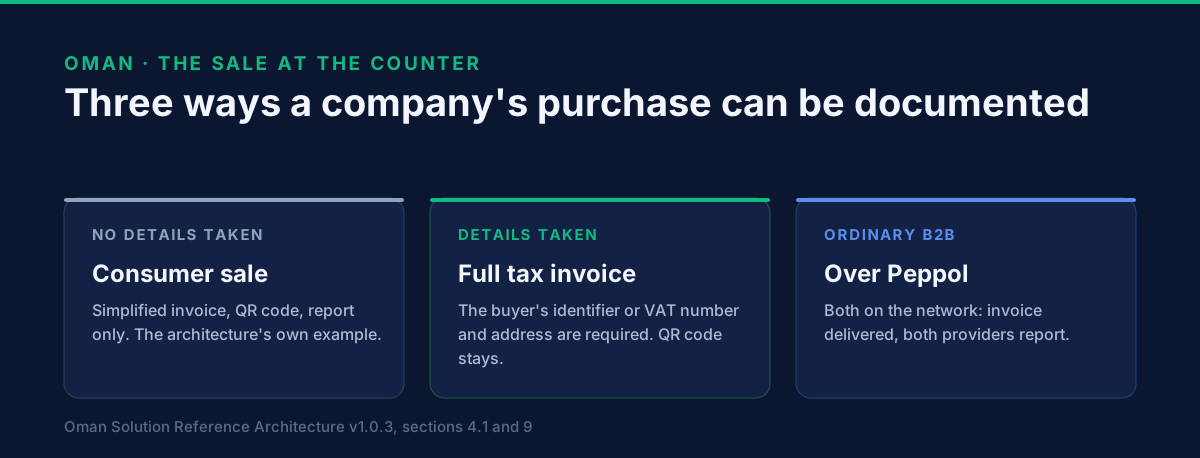
No details taken. The sale is a consumer sale. The seller issues a simplified invoice with a QR code, the file carries the fixed buyer values (General customer, country OM, substitute participant 0248:997770000099), and the seller's provider reports it. The company has a receipt. That is the architecture's stationery example.
Details taken for the sale. Note 3 says that for certain sales, "usually involving higher valued items", the seller collects more information, "including details of the buyer", even for a consumer sale, and "a different invoice type would apply". The example is a mobile phone where a warranty may apply. The rule pack shows what that other type needs. A full tax invoice requires a buyer identifier (IBT-046) or a buyer VAT number (IBT-048) under IBR-016-OM, and a full buyer address under IBR-019-OM. The QR code stays on it, because section 4.2 puts the code on a consumer invoice "full or simplified".
An ordinary business invoice. If both parties are VAT-registered and on the Oman network, section 9 gives the normal domestic business flow. The invoice is delivered from the seller's provider to the buyer's provider, and both providers send a tax data document to the Authority. If only the seller is on the network, the seller's provider reports alone, and the invoice is not delivered.
What does the architecture leave open?
Three things, and I would rather say so than guess.
- Who decides. The architecture does not say whether the seller or the buyer decides that a company's purchase becomes a full tax invoice. It says the seller "will" collect more information for certain sales. It does not say a buyer can demand a full invoice.
- Which sales. There is no value threshold, and no list of goods. It gives one example of each case.
- What the buyer can do with a consumer receipt. Whether the company can recover VAT on a purchase documented as a consumer sale is outside this page. That question belongs with a tax adviser, and with the VAT Law and Regulations.
How does GoRoute classify the buyer?
GoRoute's platform decides from the identifiers a sale carries, not from who the buyer is. The rules in the code are:
- A buyer in Oman with a Peppol ID is addressed as that participant.
- A buyer in Oman with a VAT number but no Peppol ID is addressed as the substitute
0248:997770000095, the architecture's case of a domestic buyer that is not on Peppol, consumers excluded. - A buyer in Oman with neither is addressed as the consumer substitute
997770000099, which also covers a person identified only by a civil ID. - A buyer outside Oman takes the export substitute
997770000097.
The retail counter route for shops issues simplified invoices only. It refuses a buyer that carries a VAT number or a Peppol ID, and points the sender to the invoice API, because a VAT-registered buyer needs a full tax invoice. That is a design choice in our platform, not a statement in the architecture. The architecture says only that a different invoice type applies.
How should a retailer decide at the till?
The architecture leaves the choice to the seller, so write the policy down. This part is my reading, not something the architecture states.
- Decide which sales your staff must ask a buyer's details for, such as items with a warranty. The architecture's own example is a mobile phone.
- Decide what the till does when a customer says they are a company. Either it stays a consumer sale, or the buyer's identifier or VAT number and address are captured and a full tax invoice is issued.
- Never put a business identity on a document that goes out as a consumer sale. A simplified invoice addressed to
997770000099is a consumer document, and the ruleIBR-173-OMthen requires the seller UUID. - Train staff on the difference, and test both paths before your date. How to test an Oman e-invoice before you send it shows how.
If a refund follows, how to correct or cancel a cleared Oman e-invoice explains the credit note.
What this page does not settle
The architecture's test for when buyer details are collected, the buyer's right to ask for a full invoice, and the buyer's recovery of input VAT are not in the files I read, and this page does not answer them. POS hardware is not covered. The 2027 dates are in the simplified tax invoice article.
What to do with this
Take the three outcomes above to whoever configures your tills, and ask which one each of your tills can produce today. GoRoute is an accredited Oman e-invoicing service provider. The e-invoice sending page describes how invoices are issued and reported, the Oman page gathers our Oman articles, the tutorials show it working, and the documentation has the API reference.
To talk through your own counters, book a demo.
Read next: what is in an Oman e-invoice QR code. Also in this set: profit-margin invoices.
GoRoute is accredited by the Oman Tax Authority on 29 July 2026 through Union Digital Technologies SPC, and is a certified Peppol Access Point (POP000991).
Primary sources: Oman Tax Authority — the authority that sets the e-invoicing rules; Oman Solution Reference Architecture v1.0.3 (final, 27 July 2026), sections 4.1, 4.2, 9 and 10.3.1, published by OpenPeppol with the Tax Authority; Peppol technical documentation — the PINT specification the Oman profile extends.
Frequently asked questions
- Is a company that buys at a shop in Oman treated as a consumer?
- It can be. Section 4.1 of the architecture says some consumer-sale buyers could be registered businesses and will still be treated as a consumer sale. Its example is a company buying stationery at a store.
- Does the company get a Peppol invoice for a till purchase?
- Not when the sale is treated as a consumer sale. The consumer flow has no delivery to the buyer. The seller gives a readable invoice with a QR code and its provider reports the sale to the Tax Authority.
- What happens if the company gives its VAT number at the till?
- For certain sales the architecture says the seller collects the buyer's details and a different invoice type applies. The rule pack requires a buyer identifier or VAT number, and a full buyer address, on a full tax invoice. The architecture does not say who decides when this applies.
- Does a consumer sale with buyer details still carry a QR code?
- Yes. Section 4.2 puts the QR code on a consumer invoice that is full or simplified.
- Is there a value above which buyer details are needed?
- The architecture gives none. It says only that the sales involved are usually of higher-valued items, and gives a mobile phone with a warranty as its example.
About Dr. Syed Raza
Dr. Syed Raza is an IT Enterprise Architect at ClayDesk LLC and leads the GoRoute platform. He works across Peppol Access Point and SMP infrastructure, PINT jurisdictions (Oman, AU/NZ, EU, JP, MY, SG), and national CTC regimes, translating regulatory detail into production-grade e-invoicing systems.
Building on Peppol?
GoRoute is a certified Peppol Access Point & SMP. Book a demo or read the docs to get started.