The Four New Mentions on French Invoices
Four mentions became mandatory on French invoices from 1 September 2026: customer SIREN, operation category, VAT on debits option, delivery address.
Four mentions have been mandatory on French invoices since 1 September 2026: the customer's SIREN, the category of the operation, the option to pay VAT on debits where it applies, and the delivery address of goods where it differs from the billing address. That is what the French tax administration's FAQ says. The invoice mentions that were already required stay as they are. This page lists the four, what each one contains, and the two dates that are easy to mix up.
It is written for the accountant or billing owner who has to change an invoice template or an ERP mapping. It covers the new mentions only. The older ones are not repeated, and the platform model is in France's e-invoicing mandate. GoRoute is a certified Peppol Access Point and SMP (POP000991). It is not a plateforme agréée; the list is published on impots.gouv.fr.
What are the four new mentions?
The FAQ names them in one list, and says a 2022 decree made them mandatory for invoices issued from 1 September 2026. The decree is n° 2022-1299 of 7 October 2022, which amends article 242 nonies A of annex II to the Code général des impôts. The FAQ says the new mentions are added "for data-management purposes".
| # | Mention | Applies |
|---|---|---|
| 1 | The customer's SIREN (le SIREN du client) | Always |
| 2 | The category of the operation: delivery of goods, provision of services, or both | Always |
| 3 | The option to pay VAT on debits (option de paiement de la TVA sur les débits) | Where the supplier has made it |
| 4 | The delivery address of the goods | Only where it differs from the billing address |
The first two are on every invoice. The third and fourth depend on the sale.
What goes in each one?
The customer's SIREN
The nine-digit number of the customer's legal unit. The administration's discovery page says an electronic invoice must show the supplier's and the customer's SIREN in a dedicated field. The same number is how the customer is found in the directory, which is explained in France's E-Invoicing Directory. Update your customer master data first, because this is the mention most systems lack.
The category of the operation
One of three values. The table of invoice data uses LB for a delivery of goods (livraison de biens),
PS for a provision of services (prestation de services) and LBPS where the invoice holds both. The FAQ
adds a limit to the third case: it means a delivery and a service "independent of one another". We read
that as excluding a service that is merely part of the delivery. That is our reading.
The option to pay VAT on debits
A statement that the supplier has opted to account for VAT when it invoices, not when it is paid. The table of data describes it as a mention "in case of an option for VAT on debits". If you have not opted, the mention does not appear.
It also decides something else. The administration's FAQ says payment data need not be sent for a supplier that opted for VAT on debits. Where VAT is due on receipt, the supplier reports the payment through a status, described in French E-Invoice Statuses: Which Ones Are Mandatory.
The delivery address
The address where the goods are delivered, when that is not the customer's billing address. The discovery page gives it as an example of a mention that goes in a dedicated field, "the full delivery address of the goods or service if different from the customer's address".
When does each one apply?
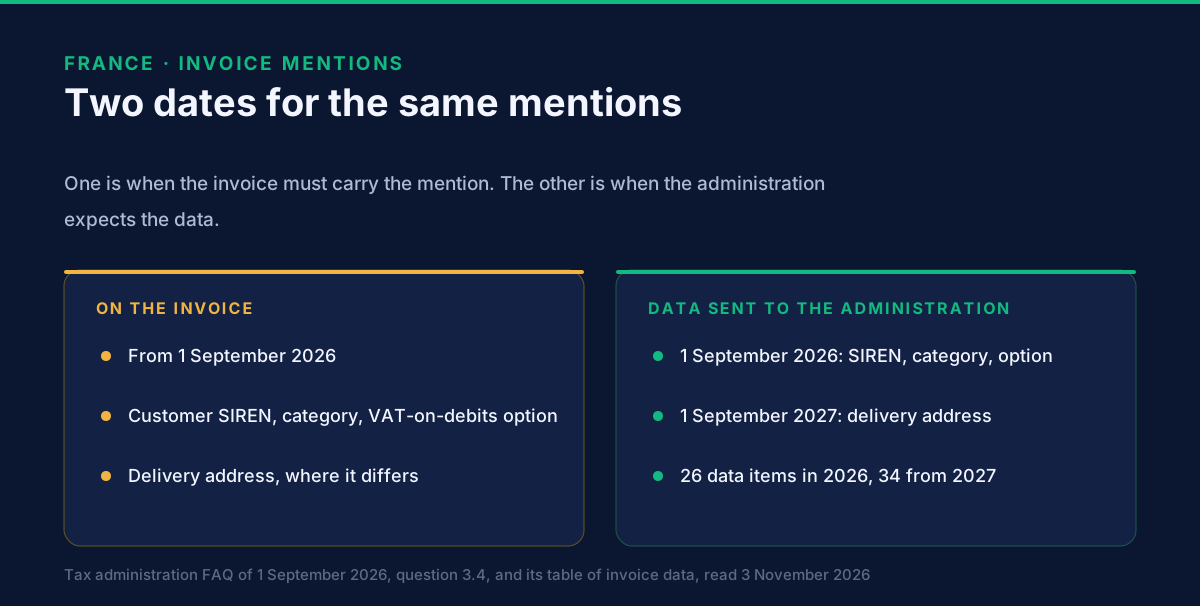
Two dates are in the sources, and they answer two different questions. One is when the mention must appear on the invoice. The other is when the data reaches the tax administration.
- On the invoice: 1 September 2026, for all four. The FAQ (version of 1 September 2026) states it.
- To the administration: the table of data to transmit (updated August 2026 on its first page, with a second page dated October 2025) gives a different date for one of them.
| Mention | Expected by the administration from |
|---|---|
| Customer's SIREN | 1 September 2026 |
| Category of the operation | 1 September 2026 |
| Option for VAT on debits | 1 September 2026 |
| Delivery address, if different | 1 September 2027 |
So an invoice issued in 2026 carries the delivery address when it differs, but the administration does not yet expect that field in the data the platform sends. The FAQ explains the staging: 26 mandatory data items in 2026, then 34 from 2027. It also explains why there are fewer data than mentions. The administration collects only what it needs, notably to pre-fill VAT returns.
We read the two documents side by side and found no conflict, but they do not say so themselves. This is our reading.
What do you change in your system?
Four edits, in this order. The sources say what the invoice must show. They do not say how any system should store it.
- Customer master data. Add the SIREN to every French customer.
- Operation typing. Decide where the goods, services or mixed value comes from in your system. That is a design choice on your side, not something the sources prescribe.
- A tax-option flag. One setting on the company that prints the VAT-on-debits mention when it is on.
- A separate ship-to address. Print and send it only when it differs from the billing address.
Your approved platform checks the invoice before it is accepted. A missing mention is the kind of fault the platform's checks can reject. See the validation errors you can prevent for how to catch faults before sending.
What is not covered here?
The older mentions, the formats, and the penalties. The FAQ says the existing mentions are unchanged, so this page does not list them. Formats are covered in the mandate guide. We give no penalty figure, because the guidance pages we read state none.
What to do next
- Check your template or ERP mapping against the four mentions above, starting with the customer's SIREN.
- Ask your platform which of the four it fills in for you and which it expects from your system.
- Read the other pages in this set: the directory, lifecycle statuses and invoicing French customers from abroad.
- To talk through e-invoicing across several countries, book a demo. The tutorials, the developer documentation and the GoRoute API show how documents reach customers on the Peppol network.
Related reading
- E-invoicing in France, the country page.
- France E-Invoicing Mandate 2026
- Invoice validation errors you can prevent
- Belgium vs France vs Germany
Sources, all read on 3 November 2026: impots.gouv.fr, Foire aux questions, je découvre la facturation électronique, version of 1 September 2026, questions 3.4 and 6.3 and 10.1; impots.gouv.fr, the same page ("modifié le 26/05/2026"); impots.gouv.fr, "Facturation électronique - Données de facture", the table of invoice data to transmit to the administration (article 41 septies D of annex IV to the CGI). Translations from the French are ours. Passages marked as our reading are not the administration's.
Frequently asked questions
- What are the four new mandatory mentions on French invoices?
- The customer's SIREN; the category of the operation (delivery of goods, provision of services, or both); the option to pay VAT on debits, where it applies; and the delivery address of the goods, where it differs from the billing address. The administration's FAQ says they became mandatory from 1 September 2026.
- Do the other mandatory mentions on a French invoice change?
- No. The administration's FAQ says the mentions required by the Commercial Code and the General Tax Code stay the same. Four are added, for data management.
- What are the codes for the operation category?
- The administration's table of invoice data uses LB for delivery of goods, PS for provision of services and LBPS for an invoice made up of both. The FAQ describes the third case as a delivery and a service that are independent of each other.
- When does the delivery address reach the tax administration?
- The administration's table of data to transmit lists the delivery address, where different from the customer's address, as expected from 1 September 2027. The customer's SIREN, the operation category and the VAT-on-debits mention are expected from 1 September 2026.
- Why does the administration collect fewer data than the invoice carries?
- Its FAQ says it collects only the data it needs, notably to pre-fill VAT returns. Collection of the structured data is staged between 1 September 2026 and 1 September 2027, with 26 mandatory data items in 2026 and 34 from 2027.
About Dr. Syed Raza
Dr. Syed Raza is an IT Enterprise Architect at ClayDesk LLC and leads the GoRoute platform. He works across Peppol Access Point and SMP infrastructure, PINT jurisdictions (Oman, AU/NZ, EU, JP, MY, SG), and national CTC regimes, translating regulatory detail into production-grade e-invoicing systems.
Building on Peppol?
GoRoute is a certified Peppol Access Point & SMP. Book a demo or read the docs to get started.