Is Verifactu Postponed to 2028? The Dates That Are Law Today
Verifactu is not yet postponed. 1 January 2027 and 1 July 2027 are still law; the Ministry only announced on 5 October 2026 that it plans October 2028.
Is Verifactu postponed to 2028?
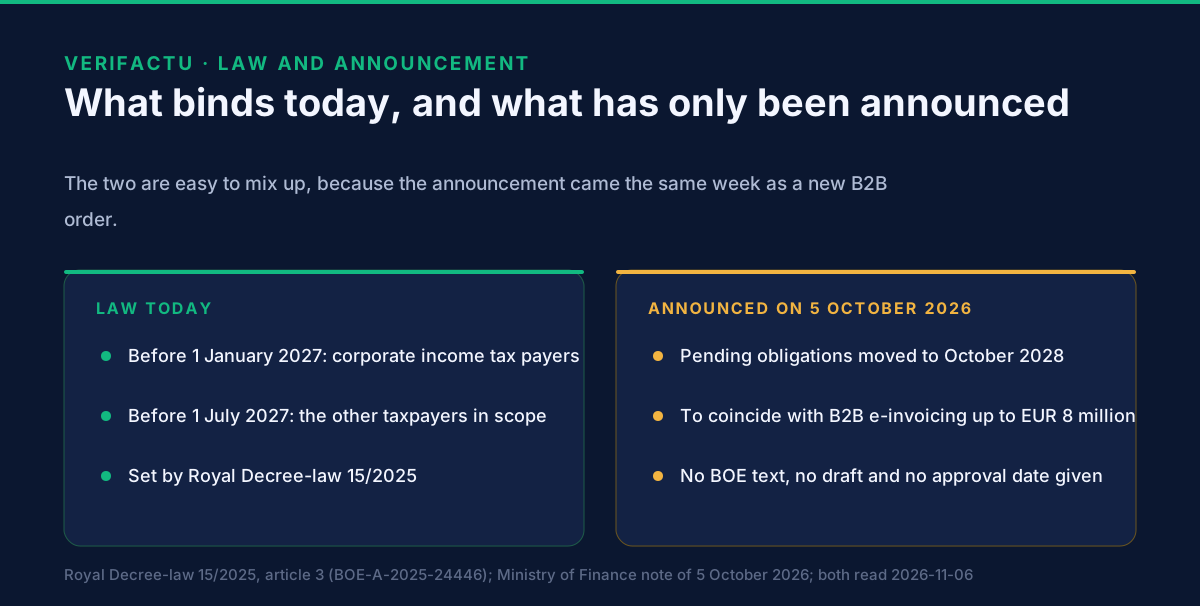
Not yet. The law still says 1 January 2027 for corporate income tax payers and 1 July 2027 for everyone else; the Ministry of Finance has only announced that it plans to move both to October 2028. The announcement came on 5 October 2026, the same day the gazette (BOE) published the order that started Spain's business-to-business e-invoicing clock. Until a legal text changes the dates, the dates in force are the ones set by Royal Decree-law 15/2025 of 2 December 2025.
| What it is | Dates | Status on 6 November 2026 | |
|---|---|---|---|
| Royal Decree 1007/2023, as amended by Royal Decree-law 15/2025 | The regulation of invoicing systems ("Verifactu") | Systems adapted before 1 January 2027 (corporate income tax payers, article 3.1.a) and before 1 July 2027 (the other taxpayers in article 3.1) | Law |
| Ministry of Finance note of 5 October 2026 | Forecast of a change to the deadlines | Pending obligations moved "until October 2028" | Announcement, no legal text found |
The sections below set out what the announcement says, what it leaves open, and what a business can sensibly do while the gap lasts. Spain's separate B2B e-invoicing mandate is the law the announcement wants to line up with.
What does the 5 October note actually say?
It says the Ministry considers it convenient to align the calendars, and therefore to postpone the pending obligations under Royal Decree 1007/2023 until October 2028. The note's heading calls it a "previsión", a forecast. Its reasoning, in the Ministry's words: to favour the maximum possible convergence between electronic invoicing systems and the invoicing-systems regulation (VERI*FACTU), both normatively and technically, it is convenient to align the implementation calendars for SMEs and the self-employed. The target is October 2028, "to make them coincide" with mandatory e-invoicing for businesses and professionals whose annual turnover does not exceed EUR 8 million.
The note makes three further points:
- A later amendment is planned. Once the alignment is approved, the Ministry will propose an amendment that aims at convergence of the scope and certain technical aspects, taking into account the future digital reporting requirements arising from ViDA (the EU's VAT in the Digital Age package).
- The core requirements stay. The requirements of Royal Decree 1007/2023 on integrity, preservation, accessibility, legibility, traceability and inalterability, and the other technical guarantees of the system, "will be maintained in substantially equivalent terms".
- It is not a legal text. The note gives no draft, no BOE reference and no date for approval.
The Tax Agency's Verifactu page lists the Ministry's note at the top. The same page, updated on 13 October 2026, still describes the 1 January 2027 and 1 July 2027 dates as the new deadlines under Royal Decree-law 15/2025, and its question-and-answer list was updated on 21 October 2026. We found no amendment to Royal Decree 1007/2023 in the BOE; the consolidated text on the BOE site was last updated on 16 September 2026.
What are the dates that are law today?
Before 1 January 2027 for taxpayers of corporate income tax, and before 1 July 2027 for the other taxpayers in scope. Article 3 of Royal Decree-law 15/2025 changed the fourth final provision of Royal Decree 1007/2023. The original date of 1 July 2025 had already moved once, through Royal Decree 254/2025, to the 2026 dates, and Royal Decree-law 15/2025 then pushed them by a year to the present ones.
"Before 1 January 2027" means that the system has to be operating by the end of 31 December 2026. Which group you are in follows from the tax you pay:
- Corporate income tax payers (Impuesto sobre Sociedades): limited companies and other entities that pay that tax, except the fully exempt entities described in article 9.1 of the corporate tax law. Their date is before 1 January 2027.
- Everyone else in article 3.1: individuals with economic activities under personal income tax, non-resident income tax payers with a permanent establishment, and income-attribution entities carrying on economic activities. Their date is before 1 July 2027.
Not everyone who invoices is in scope at all. Taxpayers on the immediate VAT information system (SII) are outside Verifactu, and the Basque Country and Navarre have their own regimes. Verifactu, SII or TicketBAI walks through who is where.
What is the test period?
The months before each date are a test period. The Tax Agency describes the time before the respective dates as a testing period, in which a taxpayer may keep invoicing with another system and may stop sending test records with a Verifactu-mode system, up to the deadline for having the systems adapted. Its FAQ includes a specific question on whether a company that chooses a Verifactu system inside that period must stay with it to the end of the calendar year; read the answer there before switching.
Can I wait for October 2028?
You can, but you would be relying on a text that does not exist yet. There are two ways it can go:
- A legal text is published and the dates move to October 2028. A business that waited loses nothing.
- No text is published before 1 January 2027, and the corporate income tax payers' date applies as written.
We cannot tell you which will happen and neither can the Tax Agency's page. The Ministry's own words on the second step, a further amendment on scope and technical details, suggest the rules may change shape and not only date. That points the same way for planning: the guarantees stay "substantially equivalent", so work done now on records, chaining and the QR code is unlikely to be wasted, while details such as which taxpayers fall in scope may still move. That reading is ours; the note does not say it.
What should you do before 1 January either way?
Find out whether your invoicing software is already adapted, and test it with the Tax Agency's test service. The work does not depend on the date:
- Confirm you are in scope. Check the SII and regional exclusions first, because a taxpayer that is outside the rules has nothing to postpone.
- Ask your software supplier for its responsible declaration. There is no certification body for these systems; the producer declares compliance itself, for each version. Ask to see it.
- Pick the mode. A Verifactu-mode system sends every record to the Tax Agency as it is issued. The alternative mode keeps and signs the records inside the system. E-invoicing in Spain compares the two.
- Test. The Tax Agency offers a test service, and the test period is the point of having one.
- Watch the BOE. If a text moves the dates, you will see it there first; the Tax Agency page will follow.
An online shop has a concrete route to all of this: Verifactu for online shops shows what a connected Shopify store does for each paid order. If you want to talk through your own system, book a session with the GoRoute team. Recorded walkthroughs, including one on Verifactu, are on the tutorials page, and the connector guide is in the documentation.
What does not change if Verifactu moves?
The business-to-business e-invoicing mandate keeps its own dates. The Ministry's announcement is about aligning Verifactu with the B2B calendar; the B2B dates come from Royal Decree 238/2026 and the Order of 2 October 2026 and are not what the note proposes to change. Spain's B2B mandate: the 2027 and 2028 dates sets them out. The note proposes no change to them, so a business above EUR 8 million of turnover should still plan for the first B2B date in October 2027.
Related guides
- Spain's B2B e-invoicing mandate: the 2027 and 2028 dates
- Verifactu for online shops: tickets, QR codes and refunds
- Verifactu, SII or TicketBAI: which system applies to you
- E-invoicing in Spain
Sources, read on 6 November 2026: the Ministry of Finance's note of 5 October 2026; Real Decreto-ley 15/2025, de 2 de diciembre, article 3, for the 1 January 2027 and 1 July 2027 dates; Real Decreto 1007/2023 for scope; the Tax Agency's Verifactu page and its notice on the extended deadline. No penalty amount is stated here because we have not read a BOE text that sets one for this question. This page describes the rules; it is not tax or legal advice. GoRoute operates certified Peppol Access Point POP000991.
Frequently asked questions
- Is Verifactu postponed to 2028?
- Not in law. On 5 October 2026 the Ministry of Finance announced that it plans to postpone the pending Verifactu obligations to October 2028. As of 6 November 2026 the dates that bind are still those set by Royal Decree-law 15/2025: before 1 January 2027 for corporate income tax payers and before 1 July 2027 for the other taxpayers in scope.
- Who has to be ready before 1 January 2027?
- Taxpayers that pay corporate income tax (Impuesto sobre Sociedades) and use an invoicing system. Everyone else in scope, such as self-employed people and entities under the income-attribution regime, has until before 1 July 2027.
- What does the Ministry's announcement say?
- That it wants to align the calendars of the electronic invoicing rules for SMEs and the self-employed and of the invoicing-systems regulation, and so postpone the pending obligations of Royal Decree 1007/2023 until October 2028. It adds that a later amendment will aim to converge the scope and some technical aspects, taking account of the EU's ViDA reporting requirements.
- Will the integrity and traceability requirements change?
- The Ministry says the requirements on integrity, preservation, accessibility, legibility, traceability and inalterability, and the other technical guarantees, will stay substantially equivalent to those in the current rules.
- When will we know for certain?
- When a legal text is published in the official gazette (BOE) that changes the dates in Royal Decree 1007/2023. Until then, the announcement has no legal effect. This page is updated when that happens.
- Can I wait until October 2028 to adapt my invoicing software?
- That would be a bet on a text that has not been published. If the text appears, the wait costs nothing; if it does not, the earlier date applies. Whether to prepare now is a decision for the business and its adviser, and this page sets out what preparing involves.
About Dr. Syed Raza
Dr. Syed Raza is an IT Enterprise Architect at ClayDesk LLC and leads the GoRoute platform. He works across Peppol Access Point and SMP infrastructure, PINT jurisdictions (Oman, AU/NZ, EU, JP, MY, SG), and national CTC regimes, translating regulatory detail into production-grade e-invoicing systems.
Building on Peppol?
GoRoute is a certified Peppol Access Point & SMP. Book a demo or read the docs to get started.